- Homebuyers
- October 1, 2026
The No. 1 Reason You Might Not Want to Root for Falling Mortgage Rates
Homebuyers likely don’t want rates to drop to pandemic-era lows below 3%. That’s not only unlikely, but also a bad sign for the economy.
Homebuyers likely don’t want rates to drop to pandemic-era lows below 3%. That’s not only unlikely, but also a bad sign for the economy.
New rules require lenders to take a deeper look at the financial health and structural condition of condominium developments before approving Conventional loans.
A mortgage recast typically lowers your monthly housing payments because you’re making a large, lump-sum payment toward your remaining loan balance.
While most buyers can’t hand over cryptocurrency to pay for a home, you may be able to use these assets in other ways to qualify for financing or cover upfront costs.
The housing market heading into the second half of 2026 looks quite different from the rollercoaster of recent years. And in many ways, that’s a good thing.
The number of U.S. homes falling into foreclosure is on the rise. For budget-conscious buyers, this might seem like an opportunity to score a bargain home for much less than market value.
One of the best resources for building your own home is a One-Time Close (OTC) Construction Loan. These loans let you finance the land purchase and construction costs together and automatically convert to a traditional mortgage loan when the home is built.
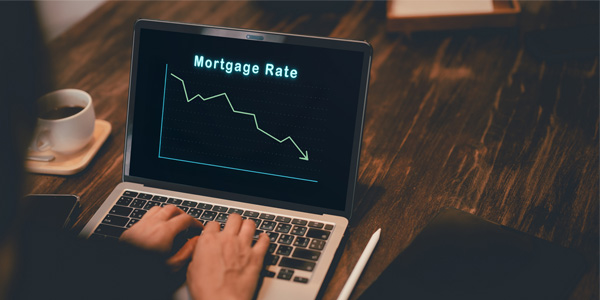
Why do interest rates move so much, and so fast? And what can you do to protect yourself? Here’s what you need to know.
If you’re self-employed, a freelancer, a gig worker, or a small business owner, you may not have the traditional income documentation lenders typically require. That’s where bank statement loans come in.
Lenders often use the 28/36 mortgage rule to ensure you can afford a home. You can also use this rule to set your own budget before you begin home shopping.
 Stay one step ahead