- Homebuyers
- June 23, 2026
Don't Panic. This is What to Do if You Receive a Low Home Appraisal
A lower-than-expected appraisal doesn't have to be a deal-killer. Here's what you should do if you find yourself in this situation.
A lower-than-expected appraisal doesn't have to be a deal-killer. Here's what you should do if you find yourself in this situation.
Many homebuyers are turning to side gigs, freelance work, and app-based jobs to help save for a down payment and closing costs. But those part-time jobs don’t always help them qualify for a mortgage.
Today’s housing market has left many would-be homebuyers asking one big question: Is it smarter to buy a home or keep renting?
If you’re buying a home, you may not want to overlook an FHA loan. These loans typically offer lower mortgage interest rates than many other types of home loans.
Mortgage discount points can be purchased by homebuyers to “buy down” the interest rate on a mortgage from the outset of the loan.
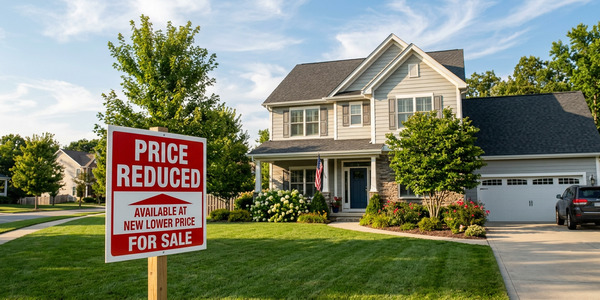
While a home with with a slew of markdowns may be a red flag, it can also create an opportunity for homebuyers to negotiate a great deal.
Thousands of down payment assistance programs across the country help buyers cover upfront costs. This is typically done with grants or low-cost loans tailored to first-time homebuyers or specific professions and regions.
FHA loans were designed to help prospective homebuyers close the deal without a huge down payment or impeccable credit. And they can be used in cities, even large ones.
With home prices high and caregiving demands on the rise, many families are turning to mother-daughter homes as a form of multigenerational living.
The good news is not all credit pulls affect your score. Even when hard inquiries are made for home loans, credit scores typically only drop by a few points and may recover in as little as a few months.
 Stay one step ahead