Housing News
Why Purchasing a Home Today Is Nothing Like Buying a Home in the ’80s
November 5, 2026
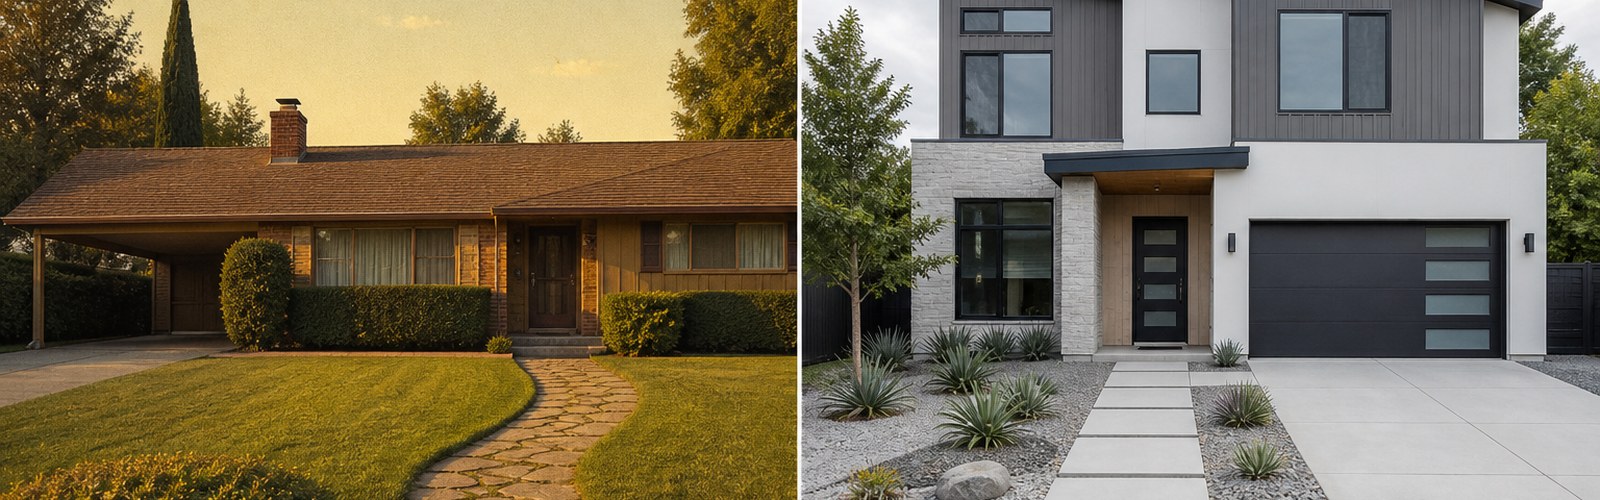
The ‘80s are back in a big way. But younger Americans saving for their first home have realized an uncomfortable truth: Buying a home today is nothing like buying a home in the 1980s.
And that’s not just because most real estate agents have stopped wearing shoulder pads.
Higher home prices relative to income, rising everyday expenses, a shortage of starter homes, and student loan debt have made it more challenging for first-time buyers to enter the housing market.
That’s not to say buying homes in the ‘80s was easy. The problems were just different, such as mortgage rates that peaked at above 18% in the early part of the decade.
“In the 1980s, the interest rate was the obstacle. Today, the price is,” explained Realtor Melanie Zimmerman, owner of MVP Chicago Real Estate.
Here’s why 1980s mortgage rates, while challenging, were less of an obstacle than today’s affordability issues.
1980s home prices were more manageable relative to income
Home prices in the 1980s looked a lot different from home prices today. But it’s even more helpful to look at home prices relative to income at the time.
“In the mid-1980s, a typical house was about 3.5 times median household income,” Zimmerman explained. “Today, it’s closer to 5 times.”
The math checks out. The median sale price for a home in 1985 was $84,300, and the median household income was $23,620 in the same year, according to the U.S. Census Bureau.
In September 2026, the median home list price was $419,250, according to Realtor.com data. The median household income was $87,460, according to the Census Bureau.
But price isn’t the only issue with today’s market. Starter homes for first-time homebuyers are also becoming harder to find.
“Builders shifted to larger homes because that’s where the margin is,” commented Alex Maldonado, a Realtor at Circle Real Estate. “Entry-level inventory barely exists, and the starter homes that do come up draw investor cash offers.”
Plus, many homeowners who purchased starter homes in the years immediately following the pandemic are hesitant to move now. Many have locked in historically low mortgage rates and may not want to sell until they see rates drop again.
Mortgage rates were higher in the 1980s
Today’s mortgage rates may feel steep compared with those following the pandemic, but they’ve got nothing on mortgage rates in the ’80s.
Rates peaked in 1981, surpassing 18%, and fell from 13% to 11% in 1985, according to Freddie Mac. Today, rates have been hovering in the low- to mid-7% range.
Still, a high rate on a cheaper 1980s home meant smaller monthly payments.
“Even though interest rates were much higher back then, homes were generally much cheaper to buy,” Zimmerman said.
High mortgage rates likely won’t last
Mortgage rates aren’t expected to remain in the 7% range forever. When they come down, many buyers will be able to refinance.
Refinancing provided a way for some 1980s homebuyers to lower their payments once rates dropped, but many didn’t have to accept the high rates to begin with.
“What people miss is that 1980s buyers had a way around those rates,” said Ryan Thomson, a Colorado real estate agent who specializes in helping buyers get assumable mortgages. “Many FHA and VA loans back then were assumable, so buyers took over a seller’s older, lower-rate loan instead of taking out a new one.”
That option still exists today, Thomson noted. Buyers who qualify to assume Federal Housing Administration (FHA) or U.S. Department of Veterans Affairs (VA) loans originated when rates were lower may be able to secure a lower rate than they could on a new mortgage.
Everyday expenses have changed, too
Today’s buyers must contend with other financial pressures, including student loan debt.
The median federal student loan balance for undergraduate borrowers entering repayment rose from $3,498 in 1990 to $18,254 in 2022, according to the U.S. Department of Education.
Health care and childcare costs have also risen substantially, putting additional pressure on household budgets. These expenses can leave prospective buyers with less money to save for a down payment or afford monthly mortgage payments.
Buyers may want to explore down payment assistance programs that can help cover these payments and closing costs. Some lenders even offer their own programs.
Shopping for a home is easier today
Today’s home prices may feel out of reach for many first-time buyers. But there’s one tool we have now that we didn’t in the 1980s: the internet.
The Sony Walkman was choice in the ’80s, but you couldn’t use it to manage your budget, contact a real estate agent, or browse home listings.
“In the 1980s, most buyers used newspaper ads or drove through neighborhoods searching for available homes,” Zimmerman explained. “Today, buyers use smartphone apps to search for homes and view listings. Once they identify properties they want to visit, they can review information, including tax implications, before viewing them.”
That convenience broadens buyers’ options, even if it doesn’t make saving for a down payment or affording a mortgage any easier.
To buy a home today, make a realistic budget and stick to it
Buying a home in the mid-2020s looks a lot different from buying one in the 1980s. Rates may be lower, but home prices and other expenses may put pressure on buyers’ budgets.
That doesn’t mean homeownership is out of reach. It requires an intentional savings plan, exploring options such as FHA loans, and flexibility about where your first home is and which amenities it includes.
Read our first-time homebuyer guide to put a plan into action.
Author
 Stay one step ahead